Project prioritization is often treated as an operational exercise: projects are scored, ranked and placed on a roadmap according to urgency or business importance. For senior management, however, the decision is more fundamental. Every approved project consumes capital, specialist capacity, management attention and the organisation’s ability to absorb change. Prioritization is therefore a form of capital allocation.
This becomes particularly important when a company has more viable initiatives than it can realistically finance or deliver. A new product may offer attractive growth potential, an IT modernisation programme may reduce long-term operating costs, a regulatory project may be unavoidable, and an automation initiative may promise a fast payback. Each can make sense independently. The difficulty is deciding which combination creates the strongest overall outcome within a limited budget and limited delivery capacity. The objective is not simply to identify good projects, but to determine which investments deserve scarce resources now, which should wait and which should not proceed at all.
Project prioritization is a capital rationing problem
In capital budgeting, companies assess long-term investments using measures such as Net Present Value (NPV), Internal Rate of Return (IRR), payback period and profitability index. These methods help determine whether the expected future benefits justify the initial investment and associated risk. The problem becomes more complex when capital is constrained. A company may identify ten projects with positive NPVs but have sufficient funding for only four. Capital rationing therefore requires management to allocate scarce resources between competing investments rather than evaluate each opportunity in isolation.
Project portfolios operate under the same principle, although financial capital is only one constraint. A company may be able to fund six transformation programmes but have enough experienced engineers to deliver only three at the same time. Two initiatives may both produce attractive returns while depending on the same technology team. Another project may offer a lower financial return but be essential for regulatory compliance or necessary to unlock value from several other investments.
Financial metrics remain valuable, but they cannot answer every portfolio question. A project with the highest expected NPV may require unavailable expertise, depend on uncertain technology or introduce delays elsewhere in the portfolio. A slightly lower-return initiative may be executable immediately and support an important customer commitment. In practice, project prioritization therefore combines financial attractiveness, strategic relevance, risk, dependencies and execution capacity.
| Evaluation dimension | Question for decision-makers |
|---|---|
| Financial value | What return, NPV, savings or cash-flow benefit is expected? |
| Strategic fit | How directly does the project support an agreed business objective? |
| Risk | What could reduce the expected value or prevent delivery? |
| Capital requirement | How much investment must be committed and when? |
| Resource demand | Are the necessary people and capabilities genuinely available? |
| Dependencies | Does the project depend on another initiative or scarce resource? |
| Urgency | What is the cost of delaying the investment? |
| Execution complexity | How difficult is delivery under current organisational conditions? |
The purpose of such a framework is not to turn management judgement into a perfect mathematical formula. It is to make the assumptions behind investment decisions visible and comparable.
Opportunity cost changes the project approval question
Organisations frequently ask whether a project is worth doing. A more useful question is whether it is worth doing instead of the available alternatives.
Approving a project consumes budget, but the less visible opportunity cost is often organisational capacity. A new digital initiative may be financially affordable while competing for the same analysts, developers, finance specialists, procurement resources or senior sponsors already required by other projects. The portfolio becomes overloaded even though every initiative has been approved separately.
A meaningful prioritization decision should therefore answer another question: what changes because this project is now a priority? If nothing is delayed, reduced or deprioritized, management may simply be adding another priority rather than making a genuine allocation decision.
This also explains why sunk costs should not determine whether an existing project continues. An initiative that has already consumed substantial investment may still deserve to be stopped if its expected future value has deteriorated or if scarce resources could produce a better return elsewhere. The relevant decision concerns the value of future spending compared with the alternatives, not the amount already committed.
Project scoring can help make these trade-offs explicit. Rather than relying solely on a sponsor’s argument or a single financial indicator, proposals can be assessed against weighted criteria such as strategic contribution, expected value, risk reduction, urgency, customer impact, regulatory importance, resource demand and complexity. The weighting should reflect the organisation’s economics and strategy rather than apply the same formula universally.
A financial-services company may assign greater weight to regulatory exposure, while a technology business may emphasise scalability and competitive differentiation. A manufacturer may give more importance to operational continuity or capacity improvement. The value of scoring lies less in producing a final number than in forcing decision-makers to explain why one project deserves priority over another.
Portfolio management connects financial value with execution reality
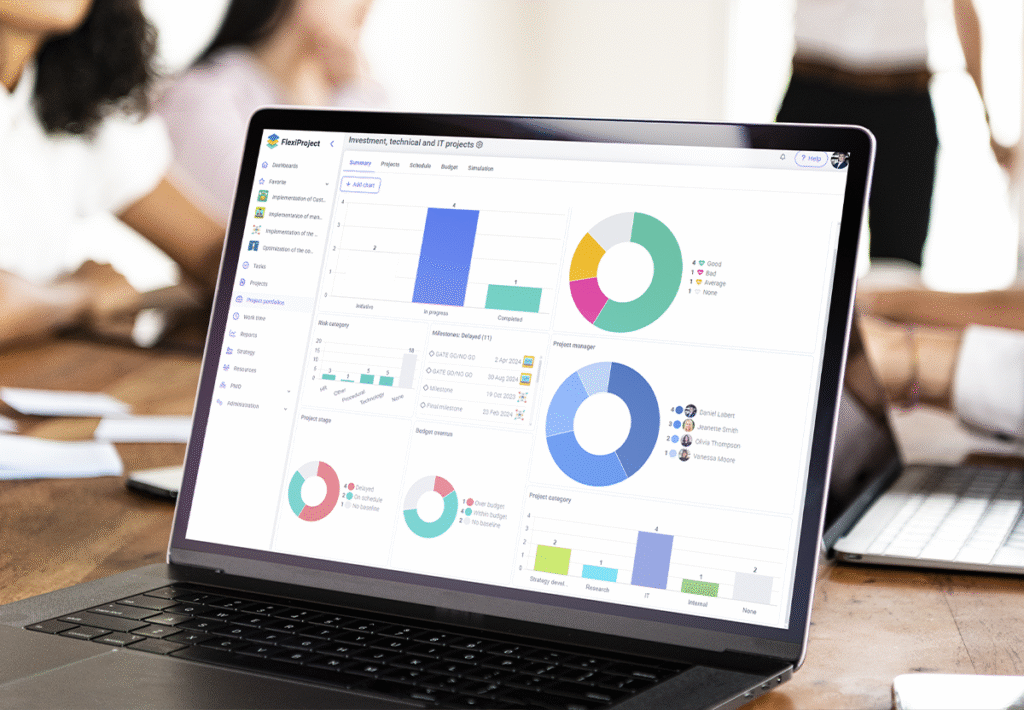
This is where a PPM software environment such as FlexiProject can support the allocation process. FlexiProject enables organisations to evaluate projects using configurable scoring models built around weighted criteria such as strategic fit, expected value, risk and complexity. Projects can also be connected with strategic objectives and their KPIs, helping management see not only which initiatives rank highly individually but whether the overall portfolio supports the intended business priorities.
The platform combines this evaluation layer with portfolio roadmaps, financial information, project dependencies, risks and resource data. Management can therefore consider not only whether an initiative is attractive, but whether it can realistically be delivered alongside the rest of the portfolio.
This distinction matters because a financially attractive portfolio can still perform poorly if several initiatives depend on the same small group of specialists. Senior architects, engineers, data experts, product owners, legal professionals or executive sponsors may become constraints long before cash does. When projects compete for those capabilities, delays affect their economics: benefits arrive later, internal costs continue for longer and resources remain unavailable for subsequent work.
A portfolio-level view makes these relationships more visible. Projects can be grouped according to strategic or operational needs, reviewed on shared roadmaps and assessed against common financial and delivery information. Portfolio risks can also be consolidated, helping management identify cases where several initiatives depend on the same supplier, system or organisational capability.
The allocation question therefore becomes broader than “Can we afford this project?” Management also needs to ask: “Can we deliver it without reducing the value of the rest of the portfolio?”
Prioritization should continue after approval
One of the weaknesses of annual investment planning is the assumption that priorities remain valid after projects receive funding. In reality, expected benefits change, costs increase, risks emerge and new opportunities appear. An initiative that ranked highly six months ago may no longer represent one of the organisation’s best uses of capital or delivery capacity.
For this reason, project prioritization should operate as a recurring portfolio process rather than a one-time approval exercise. Management needs to compare current performance and expected future value with the assumptions that justified the original decision. A project may deserve additional investment because its potential has increased, require a reduced scope because costs have risen or be stopped because the business case no longer supports continued spending.
FlexiProject supports recurring project and portfolio reviews in which schedule, budget, risk, decisions and current status can be considered within one management process. For international organisations, maintaining consistent information is also important. The system is available in 28 languages, including separate UK and US English variants, with user documentation available in 11 languages. Its mobile application allows users to review assigned tasks, update statuses, add comments and attach photographs or documents, helping distributed teams keep project information current.
The quality of the allocation decision ultimately depends on the quality of the information behind it. A project may have looked attractive at approval, but management needs current evidence to decide whether that conclusion still holds.
Project selection is only the beginning of capital allocation
Strong project prioritization does not mean choosing the initiatives with the highest headline returns. It means building a portfolio that creates the strongest achievable combination of financial value, strategic progress, acceptable risk and realistic execution.
NPV, IRR, payback period and profitability index remain important because they bring financial discipline to investment decisions. Portfolio management adds the relationships between projects: competition for resources, dependencies, shared risks and the organisation’s practical capacity to deliver change.
A project can therefore be financially attractive and still be the wrong priority at a particular moment. The better decision may be to delay it until specialist capacity becomes available, accelerate another initiative, reduce scope, or stop work that no longer supports the strongest strategic outcome.
That is why project prioritization belongs in the same conversation as capital allocation. Every portfolio decision determines where the organisation places its money, capabilities and opportunity for future growth.
Companies that prioritise well do more than select good projects. They direct limited resources towards the combination of investments most likely to create sustainable value.